

Gerald - Cash Advance

- 4.23K Reviews
- 4.4
- Downloads
- 500,000+
Our take on Gerald - Cash Advance from Appgk
When an unexpected bill lands before payday, the difference between being short for a day and being short for a week can feel enormous. Gerald - Cash Advance is a finance app built around that exact pressure point: helping eligible users access cash quickly without a traditional credit check or interest charge. I see its main value less as a replacement for a bank account and more as a short-term bridge for a tightly defined emergency.
The app comes from Gerald Technologies, Inc. and is free to install. It is rated for Everyone, which makes the presentation approachable, although the financial decisions involved still deserve adult attention. On Google Play, it has reached over half a million installs, with an average rating of 4.4 from around ten thousand ratings. Those figures suggest that the basic idea resonates with many users, but they do not remove the need to understand when a cash advance is genuinely useful and when it may simply postpone a larger problem.
What the cash advance capability really changes
The standout capability is the possibility of getting cash without relying on a conventional credit check and without paying interest on the advance. That combination matters most when a person needs a modest amount to cover a timing gap, not when they are trying to finance an ongoing lifestyle or a large purchase.
In practical terms, the appeal is straightforward. A traditional loan may involve credit history, interest, and a longer repayment structure. A credit card can solve the immediate shortage but may create a balance that becomes expensive if it is carried. Gerald’s approach is designed to feel more contained: use the advance for the immediate need, then deal with the repayment rather than allowing interest to accumulate.
Best Parts of Gerald - Cash Advance
Things to Keep in Mind About Gerald - Cash Advance
That does not make the money free. The absence of interest should not be confused with the absence of responsibility. I would still treat every advance as money already committed from my next available funds. The useful question is not only, “Can I receive this now?” but also, “Will repayment leave enough room for rent, food, transport, and other fixed obligations?”
This distinction is the most important thing to understand before using the app. A no-interest advance can be less costly than revolving credit, but it can still create a second cash shortage if the original problem is not temporary. Gerald works best when the gap has a clear end, such as a delayed paycheck or a bill that arrives a few days earlier than expected.
News and Features Related to Gerald - Cash Advance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
My first impression of the purpose
I found the app easier to evaluate when I stopped thinking of it as a general-purpose banking replacement. Its strongest identity is a short-term cash tool inside the broader finance category. That narrower purpose is also its advantage: someone who needs a quick bridge may not want the complexity of applying for a conventional personal loan.
The developer, Gerald Technologies, Inc., has kept the central promise easy to understand. The app’s store summary focuses on fast cash, no credit check, and no interest. Those are meaningful points for users who have limited credit history or who want to avoid adding interest-bearing debt. They should be read as an invitation to examine the offer carefully, not as a reason to borrow automatically.
Don't want to read the full review?
One practical tip is to decide the repayment source before requesting anything. If the answer is a specific upcoming paycheck or a confirmed deposit, the advance has a clear role. If the answer is “I will figure it out later,” I would skip the transaction. That simple test prevents the app from becoming a cycle rather than a bridge.
How using it fits into an everyday money problem
Imagine that my phone bill and a necessary prescription fall due during the same week, while my next paycheck is several days away. I could put one expense on a credit card, ask a friend, or apply for a conventional loan. Each option has a different cost or social consequence. Gerald may offer a more direct route if I qualify and the amount available covers the immediate need.
Screenshots
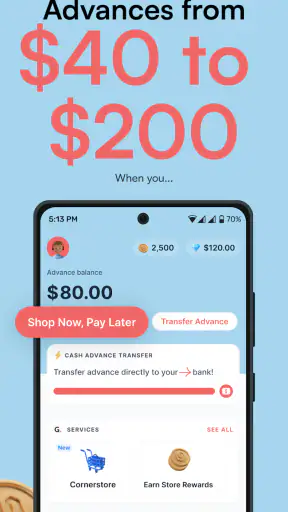
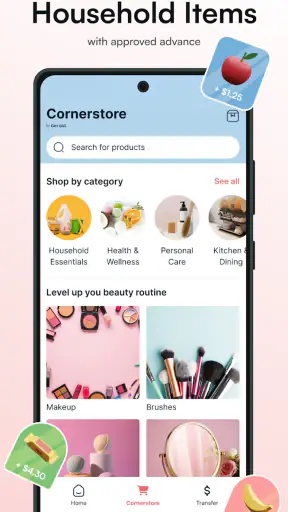
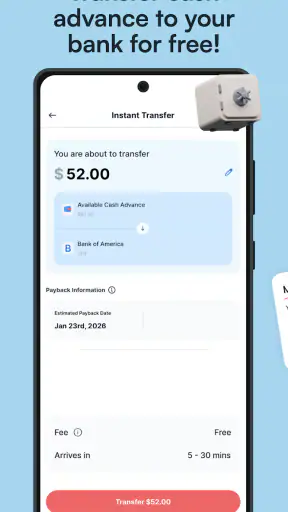
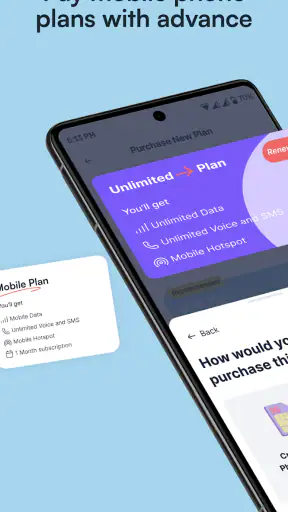
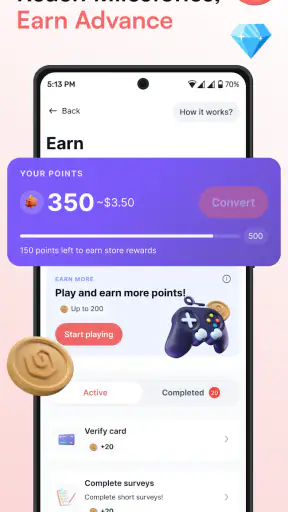
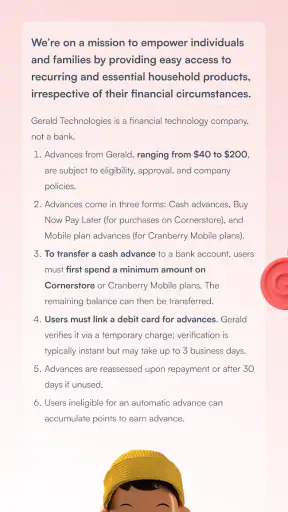
In that situation, I would open the app, review the advance terms shown to me, and check the repayment timing against my actual income calendar. I would not rely on memory. I would compare the expected repayment with the balance needed for essentials and make sure the advance is being used for the urgent bill rather than for optional spending.
The workflow is especially sensible when the expense is predictable and isolated. A car repair needed to keep getting to work, a utility payment that cannot wait, or a small medical expense can each justify considering a short-term advance. The common thread is that the expense protects stability and that repayment has a realistic source.
Where the experience can become less comfortable is during eligibility and delivery. A user may assume that an advance is guaranteed simply because the app advertises the capability. In reality, access can depend on the individual situation and the details presented during the request. I would therefore avoid making a same-day payment plan that depends entirely on money arriving before I have reviewed the final offer.
That is one of the less obvious trade-offs of fast financial apps: speed is valuable, but speed can encourage rushed decisions. I recommend treating the confirmation screen as a pause rather than a formality. Check the amount, the repayment date, and any conditions displayed there. If the result does not match the need, canceling the request is better than borrowing more than necessary.
A useful routine before requesting an advance
I would use a three-step routine. First, write down the exact bill and the minimum amount needed. Second, identify the income that will cover repayment. Third, leave a small cushion for ordinary expenses between now and then. This approach is more reliable than requesting the maximum amount simply because it appears available.
Another useful habit is to separate urgent spending from convenience spending. If I am tempted to use the advance for shopping, entertainment, or an upgrade, that is a sign the tool is being used for access rather than necessity. Gerald is most defensible when it prevents a concrete consequence, such as a late payment or an interruption to an essential service.
I would also keep a personal note of the repayment commitment instead of assuming the app will be the only reminder I need. A calendar entry can make the future deduction or repayment feel real today. This is a small step, but it helps prevent the common mistake of mentally spending the same money twice.
The situation where Gerald makes the most sense
The best scenario is a short, clearly defined mismatch between income and an essential expense. For example, if I know money is arriving shortly but a necessary bill cannot be moved, a no-interest advance may be preferable to carrying a credit-card balance. It can also be more comfortable than asking someone close to me for help, especially when the gap is small and repayment is predictable.
People with limited or damaged credit may find the no-credit-check aspect particularly relevant. Conventional lenders often make credit history central to the application, while Gerald’s proposition is aimed at a different kind of assessment. That can make the app worth examining for someone who would otherwise have few formal options.
Still, I would not describe this as a universal solution for people with poor credit. If the underlying issue is unstable income, repeated overdrafts, or a monthly budget that is already short, another advance may only move the pressure forward. In that case, a nonprofit financial counselor, a payment arrangement with the biller, or a more sustainable budgeting plan could be a better direction.
There is also a timing benefit. A small advance can help avoid a high-cost alternative when the choice is between waiting for income and using a product that charges interest. But the comparison should include every condition shown in the app, not just the headline interest rate. A product can be interest-free and still require careful attention to repayment and eligibility.
Three decisions that improve the experience
- Borrow only the gap: Request enough to solve the immediate problem, rather than treating the available amount as a spending limit.
- Match the advance to a known inflow: A confirmed paycheck or other dependable deposit gives the repayment plan a firm foundation.
- Use alternatives before borrowing: Ask whether the bill can be delayed, split, or paid through an existing interest-free arrangement before creating a new obligation.
These choices may sound obvious, but they change how the app functions in real life. Used carelessly, a fast advance can hide a budget problem for a few days. Used deliberately, it can prevent a small timing issue from becoming a late fee, a missed essential payment, or an expensive revolving balance.
Trade-offs I would consider before relying on it
The biggest limitation is that convenience can make borrowing feel less serious than it is. The app’s friendly, accessible presentation reduces friction, which is helpful during an emergency but potentially risky for impulsive users. I would not open it while distracted, stressed, or shopping. I would open it with the bill and repayment plan already in front of me.
A second limitation is that no credit check does not mean every user receives the same access. The amount, timing, and eligibility shown in the app may not match what a person expects. This is why I would never schedule an essential payment solely on the assumption that the advance will be approved or delivered exactly when needed.
A third trade-off involves recurring use. One isolated advance can address a temporary gap. Several advances in succession indicate that the budget is not recovering between pay periods. At that point, the app may be functioning as an income substitute, which is a much more dangerous role. I would consider repeated use a signal to step back and review fixed costs, payment dates, and available support.
Compared with a credit card, Gerald’s interest-free positioning can be attractive for a short bridge, especially for someone who wants to avoid carrying a balance. A credit card may still be better for purchases that need dispute protections, broader acceptance, or a longer planned repayment period, provided the user can pay it responsibly. The two tools solve different problems and should not be treated as interchangeable.
Compared with a conventional personal loan, Gerald appears more suited to a smaller and more immediate cash need. A bank or credit union loan may be more appropriate when the expense is larger, the repayment must be spread over a longer period, or the borrower wants a more formal installment structure. The extra application effort may be worthwhile when the problem cannot be solved within one short income cycle.
Compared with borrowing from family or friends, the app offers privacy and a formal digital process. On the other hand, a trusted person may offer more flexibility if repayment timing changes. I would choose based on the relationship, the urgency, and the certainty of repayment rather than assuming one option is always superior.
Device compatibility is also worth checking before installation. The current version is 69.0.9, and the app requires Android 7.0 or later. That covers many older Android phones, but anyone using an especially old device should confirm that the operating system meets the requirement before depending on the app during an emergency.
Who gets the most value from it
Gerald is a strong candidate for someone who has a temporary cash-flow mismatch, wants to avoid interest, and can identify exactly where repayment will come from. It may also suit a user who does not want a traditional credit inquiry to determine whether a small emergency can be handled. For those people, the app’s focused purpose can be more useful than a broad financial product with a longer application process.
I would be more cautious recommending it to anyone whose income varies sharply, whose essential bills already exceed monthly income, or who is considering an advance for discretionary purchases. The same convenience that helps one user avoid a costly short-term problem can make another user’s debt pattern harder to see.
It is also not the right first choice for a large planned expense. If I need months to repay, I would compare credit-union lending, a structured personal loan, an employer-supported option, or a negotiated payment plan. Gerald’s value is strongest when the need is immediate, limited, and temporary.
The app is free to download and carries an Everyone content rating, but those labels do not replace financial judgment. I would read the in-app details each time rather than assuming that a previous experience will be identical to the next one. Financial products can be sensitive to personal circumstances, and a familiar interface should never become a reason to skip the terms.
My final take after weighing the real use case
I like Gerald’s central idea because it addresses a common problem without automatically pushing users toward interest-bearing debt. The no-credit-check and no-interest focus can make a meaningful difference when a person is facing a brief, specific gap and has dependable money coming soon. In that narrow situation, it is a practical option worth considering.
My recommendation comes with a firm boundary: use it as a bridge, not as a second paycheck. Before requesting cash, confirm the exact amount needed, the repayment timing, and the effect on the rest of the budget. If those answers are clear, the app may help resolve an urgent expense with less friction than a conventional loan or revolving credit.
If the answers are unclear, I would choose a slower but more sustainable alternative. Gerald cannot turn insufficient income into sufficient income, and no-interest borrowing can still become stressful when repeated. For the right user and the right moment, however, its focused cash-advance capability is genuinely useful. That is why I see it as a sensible emergency tool, provided the person using it remains in control of the repayment plan.
Gerald - Cash Advance FAQ
What is Gerald - Cash Advance, and how does it work?
Gerald is a financial app designed to give eligible users access to cash advances and other money-management features. After creating an account and completing the required identity and eligibility checks, you may be able to request an advance based on the information available in your profile. Approval, advance limits, timing, and repayment conditions can vary, so review the terms shown in the app before accepting any offer.
Who can use Gerald, and what information is required to sign up?
Availability depends on factors such as your age, location, identity, banking details, and other eligibility requirements established by Gerald. During registration, the app may request personal information, a government-issued identification document, access to a supported bank account, and details about your income or employment. Requirements can change, and completing registration does not guarantee approval for a cash advance.
How much money can I receive through Gerald, and when will it arrive?
The amount available through Gerald is not necessarily the same for every user. Your limit may depend on account history, verified information, recurring income, and the app’s current eligibility assessment. Delivery speed can also differ according to the transfer method and your bank. Some options may be faster than standard transfers, while additional conditions or charges may apply.
Are there fees, interest, subscriptions, or repayment charges?
Before using Gerald, carefully check the complete cost of each feature. Depending on the product and your account, costs may include membership or subscription charges, optional expedited-transfer fees, or other service-related expenses. A cash advance may have different terms from a traditional loan, but that does not mean it is cost-free. Confirm the total amount due, payment date, and cancellation rules before proceeding.
Is Gerald safe, and what should I consider before downloading it?
Gerald may use security measures and identity verification to protect accounts and financial information, but no financial app can eliminate every risk. Download it only from the official Google Play Store or Apple App Store, check the developer name and permissions, and avoid sharing login codes. Also read the privacy policy, user agreement, repayment terms, and customer-support information before linking a bank account.











